Black Friday Is Coming. Customs, Take Note.

An Aruba court restored a USD 3,200 customs value that Customs had raised to USD 6,000. Before Black Friday: a bargain is not fraud, and the law sets the test.
Halloween is around the corner, and Black Friday follows soon after. For many people in Aruba, that means ordering products online at substantial discounts. Businesses will also take advantage of promotions abroad to purchase inventory at prices considerably below what those same goods normally cost.
So this may be a good moment for Customs to do some homework or, better yet: “...come to the front of the class…”.
A recent decision of the Court of First Instance of Aruba should be required reading. The case concerned an item purchased abroad for USD 3,200. The buyer had substantial documentation supporting the transaction, including a bill of sale, proof of payment, and communications with the seller. Customs did not accept the declared value and instead valued the item at USD 6,000, relying substantially on higher reference and asking prices found online.
The Court said: not good enough.
Customs did not sufficiently investigate the item's relevant characteristics, and the material it relied on was insufficient to justify disregarding the transaction value. The Court restored the customs value to USD 3,200.
With Black Friday approaching, that decision could hardly be more timely.
Free competition sometimes produces a bargain
The starting point is the law. In the law, our customs valuation rules refer to the “normal price” essentially the price independent parties can reach under conditions of vrije mededinging, or free competition. Those words matter because a competitive market does not produce one magical price for every product. Sellers discount. Businesses clear inventory. Demand changes. Merchandise sits unsold. Buyers negotiate. Retailers run promotions. Sometimes a seller needs to move merchandise quickly, and sometimes a buyer simply negotiates an excellent deal.
That is not a market failure. That is the market.
The legislative history the Court discussed recognizes this commercial reality. The buyer tries to obtain the goods as cheaply as possible, while the seller tries to get the highest price possible. If the parties are independent and no special relationship influences the transaction, the price they ultimately reach can represent the normal price.
Black Friday is perhaps the easiest way to understand this. A product normally advertised for USD 1,000 may legitimately sell for USD 500. Another retailer may still ask USD 950, while someone else may ask USD 1,100. Finding those higher prices online does not prove the USD 500 transaction didn't happen. An asking price is what somebody hopes to receive. A transaction price is what somebody actually agreed to pay. That distinction apparently needs emphasizing.
Suspicion is not the legal test
The Court made another important point. When Customs wants to reject the declared customs value, the burden rests on Customs to make it plausible that the declared value does not represent the normal price and that a higher value should be applied. But before Customs gets there, it must remember what the law requires it to determine.
The legal test is not whether a customs officer personally thinks the price is too low or Googles around and finds a high price. It is not whether the price looks unusual. It is not what the officer would have paid, what somebody else is asking online, or what Customs believes the item “should” be worth. The law provides the framework for answering the valuation question: what price can be reached for the goods between independent parties operating under conditions of vrije mededinging, or free competition?
This is not merely one consideration among many that a customs officer may accept or disregard. It is the legal framework that disciplines the valuation exercise.
That framework matters because free competition necessarily produces different prices. Buyers try to buy cheaper. Sellers try to sell higher. Demand changes, negotiations happen, sellers accept less than they originally wanted, and promotions occur. Sometimes one buyer simply gets a much better deal than another. Customs therefore does not have unlimited discretion to decide that a price “feels wrong” and then construct a theory of what the goods ought to be worth. The officer's task is narrower because the law limits it, and customs must follow the law.
Customs must return to the legal test. Were these independent parties? Was the transaction reached under conditions of free competition? Is there evidence concerning the actual transaction demonstrating that the declared price does not represent the normal price within that legal framework? If Customs rejects that value and substitutes a higher one, can Customs substantiate that decision?
Those are the relevant questions, and here's a tip for Customs: any purchase anyone in Aruba makes on a website like Amazon.com is a transaction between 2 independent parties.
A higher asking price found somewhere on the internet does not change the legal test. A customs officer's thinking does not change the legal test. An internal practice does not change the legal test. Customs cannot go beyond the law simply because somebody believes another method of valuing the goods makes more sense. In fact, civil servants like customs officers take an oath to apply the law. Maybe they forgot.
Customs is bound by the legal framework. That is why the burden the Court identified matters. Once Customs rejects the declared value and wants to impose a higher one, it must make this plausible and document it, not merely raise a chest, that the declared value is not the normal price within the meaning of that legal framework and that the higher value should apply. Subjective opinions are not the legal test, and it certainly is not the answer. The law supplies the test. Customs supplies the hard evidence, the proof, not a subjective opinion. The customs guy does not get to supply a different law.
Let me make one thing clear, because Customs has insulated itself otherwise before. The law doesn’t set a maximum discount a buyer/importer can get. If a customs officer ever tells you this, ask him to put it in writing on customs letterhead, with his full name and rank.
Customs does not make the law
This is where the issue becomes much larger than one USD 3,200 transaction. Customs valuation does not begin with the opinion of the officer standing at the border. There is a legal hierarchy. At the treaty level sits Article VII of GATT 1994, which forms part of the higher-order framework underlying our customs valuation system. Domestic customs legislation is built on that framework. There are statutory procedures. Courts interpret and apply those rules.
Then there is Customs.
Customs is at the administrative end of that legal chain. It does not sit above it. Customs does not make law. Customs follows the customs law.
The principle of legality means public power requires a legal basis and must remain within the boundaries that basis imposes. Administrative convenience (or pretens) does not create additional powers. Institutional habit does not create additional powers. An officer's opinion does not create additional powers.
Legal certainty (“rechtszekerheid”) matters too. Citizens and businesses must understand the rules the government applies and organize their affairs accordingly. The law cannot be quietly replaced by an informal administrative practice.
Proportionality and subsidiarity (‘proportionaliteit en subsidiariteit”) impose further discipline. A legitimate governmental objective does not automatically justify every intervention that might help achieve it. Use the proper legal instrument for the proper purpose, under the conditions the law attaches to it, and consider whether a less intrusive lawful measure can achieve the legitimate objective. These principles are not obstacles preventing Customs from doing its job. They are requirements for doing the job lawfully.
Know which power you are exercising
Another example should prompt some institutional reflection within Customs. I know of a separate customs dispute in which Customs escalated the matter into the criminal sphere and filed a criminal complaint against an importer. The matter ultimately did not proceed; the Prosecutor dismissed the criminal charge. Essentially, the prosecutor told Customs: “not so fast Jack!”
That was a different matter involving different legal issues. But together with the recent valuation judgment, it raises a broader institutional question: Does Customs sufficiently understand the limits and proper purposes of the powers entrusted to it? Criminal law is not an administrative exclamation mark. It should not be used simply because somebody wants to add “teeth” to a dispute. Criminal law is an ultimum remedium. Every first-year law student learns this. The existence of administrative, fiscal, and criminal instruments does not give an administrative authority the freedom to choose (or cherry-pick) whichever instrument produces the greatest pressure.
The legal nature of the problem matters. The legal framework matters. The purpose for which a particular power was granted matters. The conditions governing its use matter. Proportionality matters. Subsidiarity matters.
A public authority should not ask, “What is the biggest hammer we have?” It should be “What does the law authorize us to do in these circumstances, for this purpose, and under these conditions?”
That is the difference between possessing power and lawfully exercising public authority. That concern is not entirely theoretical. Customs' own website offers an interesting glimpse into its institutional emphasis. On its page on “Overtredingen en misdrijven” the language quickly moves toward the punitive end of the enforcement toolbox: detention or seizure of goods, a proces-verbaal, possible arrest, referral to the Public Prosecutor, and criminal prosecution. Customs addresses administrative and fiscal procedures elsewhere on its website, so the point is not that those instruments don't exist. The point is what Customs chooses to emphasize when it speaks about violations. That page offers little sense of a graduated enforcement philosophy that first asks which legal instrument fits the particular situation. Perhaps that deserves some institutional reflection. The existence of a criminal power should never create a criminal reflex.
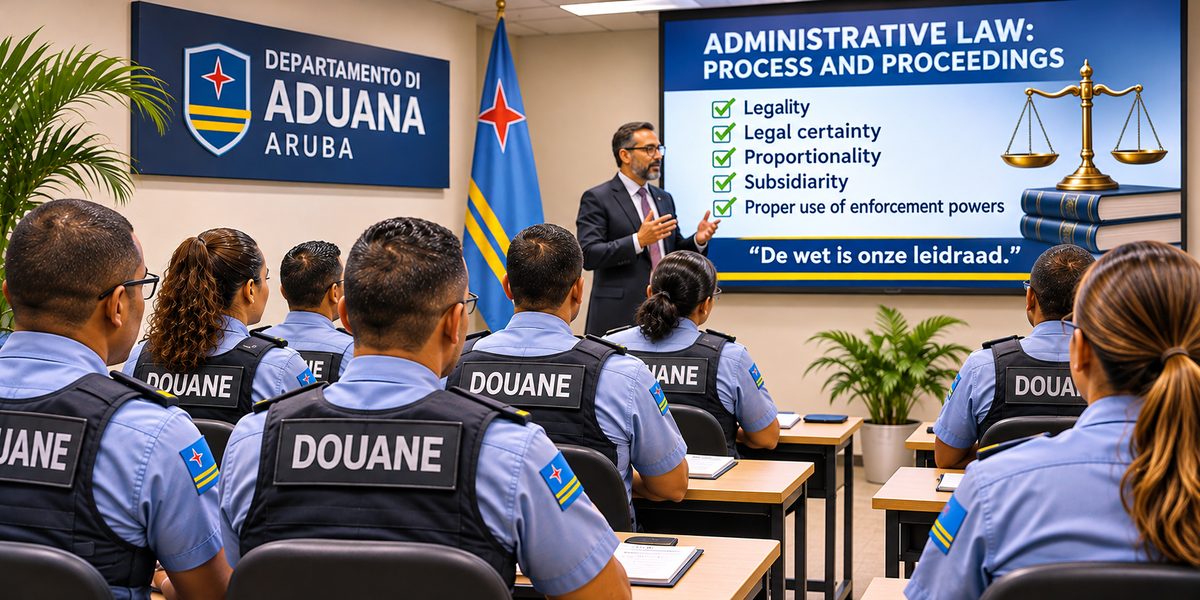
Perhaps Departamento di Aduana should consider organizing (basic) (refresher) training for its staff on administrative law, administrative proceedings, and, in particular, the proper use and limits of public powers. Such training could revisit the principles of legality, legal certainty, proportionality and subsidiarity, as well as the distinction between administrative, fiscal and criminal instruments. After all, Customs itself identifies professionalism as one of its core values and states on its website:
“De wet is onze leidraad.”
If the law is truly your guide, then understanding which power the law gives you, for what purpose, under what conditions and subject to which limits should be at the very heart of the job.
That is not an attack on Customs. It is what we should expect from any public authority entrusted with significant powers over citizens and businesses. The greater the power, the greater the discipline required in exercising it.
Learn the lesson once
I have one more point to make directly to Customs. An administrative authority should not read a court judgment, file it, forget it, and then wait for the next citizen to finance the same lesson all over again. If another importer arrives tomorrow with another motorcycle purchased under materially similar circumstances, Customs should not repeat unsupported reasoning and effectively say: “If you disagree with us, hire a lawyer.”
Citizens should not have to spend thousands of florins merely to force an administrative authority to apply a legal standard a court has already explained. Government should learn from losing a case. The public should not have to keep paying tuition for government's education. When a court explains how the law operates, a responsible administrative authority (read: the chiefs of customs) studies the judgment, reviews its procedures, educates its officers and, when materially similar circumstances arise again, applies the law consistently. Otherwise, every citizen is effectively required to purchase his own copy of the rule of law through litigation. That cannot be right.
You are civil servants
Customs officers exercise significant public authority over businesses and ordinary citizens, but remember whose authority it is. It is not the officer's personal authority. The law confers it for a public purpose and subjects it to legal limits.
Customs officers are civil servants. The public pays them to administer the law in the public interest. That does not mean being soft on fraud. It means that whenever Customs exercises public power, it must identify its legal basis, satisfy the conditions governing its use, follow the prescribed procedure, and support the resulting decision with the evidence the law requires. Public authority is not personal sovereignty. The uniform gives you authority. It does not give you sovereignty.
Customs should also remember its economic role. Businesses and individuals create the transactions. They purchase, sell, import, invest, and assume commercial risk. Customs performs the governmental function of administering the border and collecting the duties legally due on that economic activity. Customs is not an economic driver; commerce is. Success is not collecting the highest amount possible. Success is applying the law correctly and collecting exactly what the law requires, no less, but certainly no more.
If Customs believes the law produces the wrong result, our democratic system provides mechanisms to change the law. Make the argument to Government. Convince Parliament. If you want to make the rules yourself, enter politics, get elected and change the law; until then apply it. You cannot change the law through administrative practice. Until the law changes, obey the law. Apply the treaty framework. Apply the domestic legislation. Use the statutory procedures. Respect the courts. Understand the limits attached to each power. Apply those rules consistently to the next citizen who walks through the door.
Black Friday is coming
All of this brings us back to Black Friday. In the coming weeks, perfectly legitimate goods will arrive in Aruba at prices substantially below what someone may find online after the promotion ends.
So if you get an exceptional deal, document the circumstances properly. Your invoice is already part of the import process. With an unusually good price, the key is to preserve additional evidence showing how you reached that price. Take screenshots of the promotion, preferably showing the date and time. Preserve the promotional terms and discount codes. If the price was negotiated directly, keep the correspondence showing how the final amount was reached. By the time the goods reach Aruba, the promotion may be gone, and the regular price may have returned. You should be able to demonstrate the commercial reality that existed when the transaction took place.
But Customs must equally respect the legal reality governing the valuation.
So Customs, take note before Black Friday arrives. Educate your officers. Study the law you administer, the treaty framework behind it, and the recent judgment. Understand what vrije mededinging actually means. If in doubt, go ask the Aruba Fair Trade Authority. Understand the evidentiary burden. Understand legality, legal certainty, proportionality and subsidiarity. Understand the distinction between administrative and fiscal powers and the exceptional role of criminal law. Know the source of your powers, the conditions attached to them and their limits. Most importantly, know your place in the legal hierarchy.
A bargain isn't fraud just because someone at Customs thinks the buyer got too good a deal. Sometimes USD 3,200 really is USD 3,200. And the Black Friday price really is the price.
Have a wonderful week, enjoy your online shopping, and stand your ground. I will see you again next week. In the meantime, visit my new website, www.lincolngomez.com, where you can find all my blogs and podcasts.
24 October 2026